Guides
What your Monte Carlo success rate really means
Most retirement planners give you one number from a Monte Carlo simulation: your 'chance of success.' It's useful — but only if you know what it's measuring and what it leaves out.
Updated October 2026
What the percentage measures
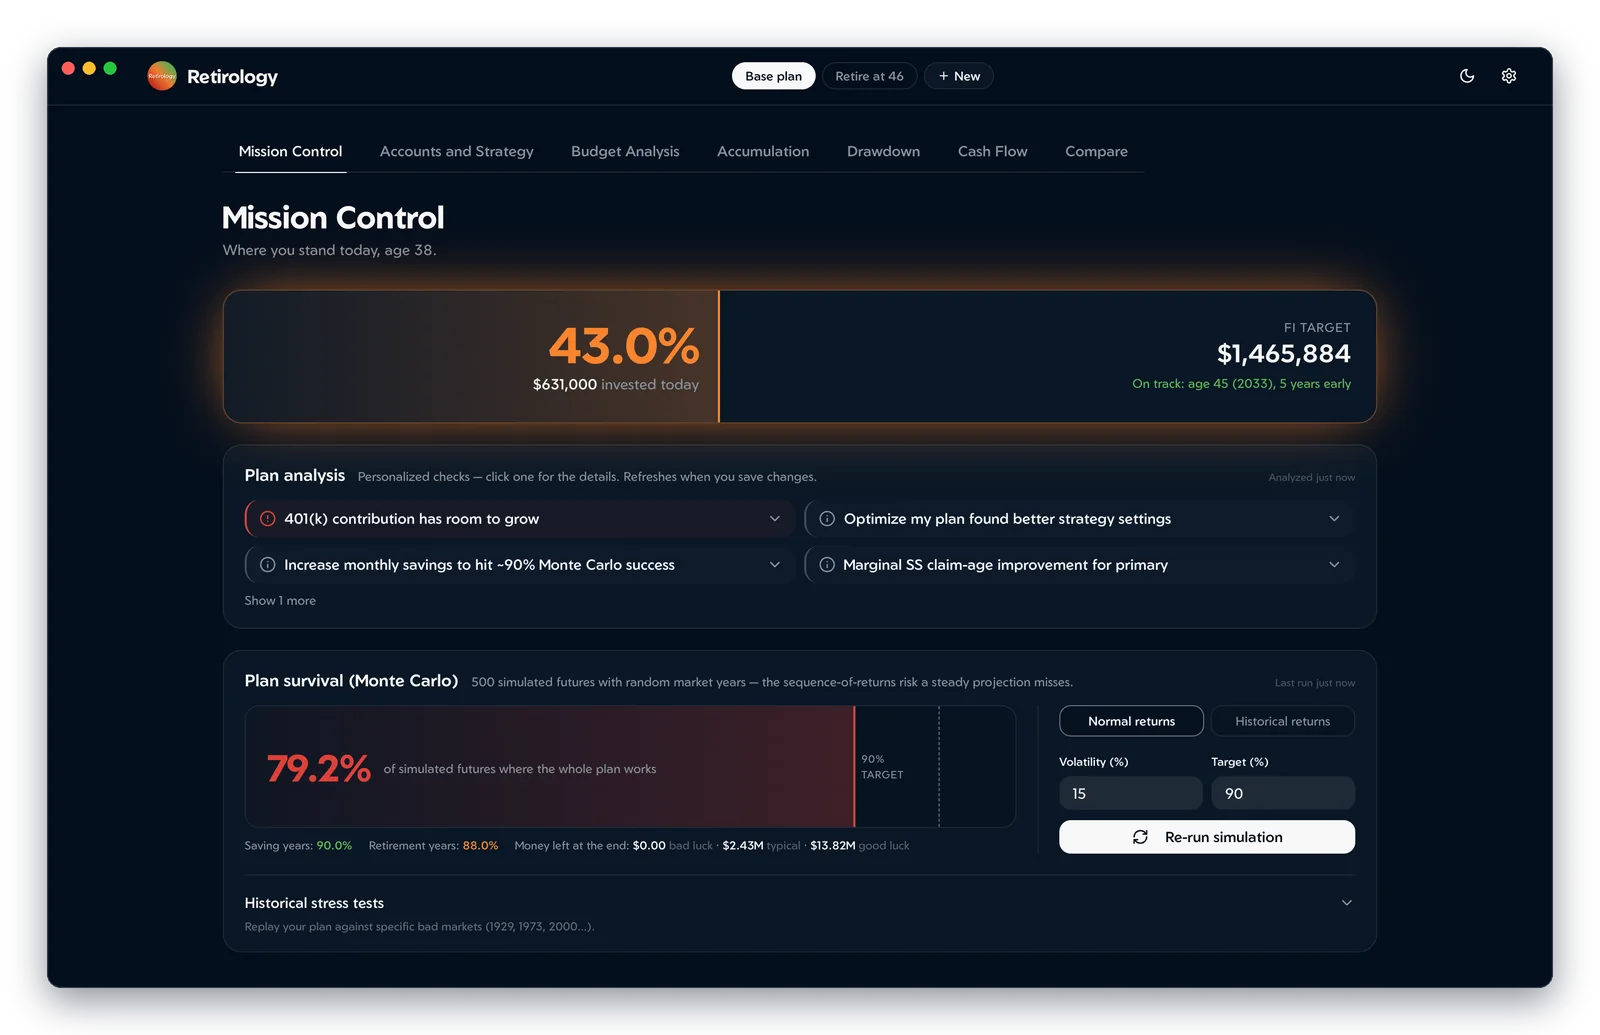
A Monte Carlo simulation runs your plan hundreds or thousands of times, each with a different random sequence of market returns. Your success rate is the share of those runs where the money lasts through the end of the plan.
A single straight-line projection assumes the same return every year. Real markets don't work that way, and the order of returns matters: a crash in your first few years of retirement, while you're withdrawing, does far more damage than the same crash ten years later. That's sequence-of-returns risk, and it's what Monte Carlo is for.
Why 100% is the wrong goal
Chasing 100% means planning for the worst market in history and then some. The cost is real: more years of work, or less spending in the years you're healthiest. And "failure" in a simulation is rarely what it sounds like:
- The model usually holds spending fixed. Real retirees trim spending after a bad year, and even modest flexibility raises success rates sharply.
- Social Security and pensions keep paying even if the portfolio runs low.
- Most failures happen late in a long plan, which gives you years of warning.
That's why many planners treat 80%–95% as a sensible range, especially for a plan you'll revisit each year.
Look at more than one number
- Bad-luck outcomes. Two plans can both show 90% while one leaves a $200,000 cushion in the worst 5% of futures and the other leaves $1.5 million. Look at the 5th percentile, not just the success rate.
- Saving years versus retirement years. A plan can fail because you don't reach your target by your retirement date, or because the money doesn't last afterward. They call for different fixes.
- Historical stress tests. Replaying a real sequence — retiring in 1929, 1973, 2000, 2008 or 2022 — shows concretely when and how badly a plan would have bent.
The assumptions that move the number
- Volatility. Higher volatility spreads the outcomes; at the same average return, more runs fail.
- Expected return and inflation. A 1-point change in either can move the result by more than any strategy tweak.
- Plan length. Planning to 95 instead of 90 adds five more years to survive.
- Normal or historical returns. Historical sampling keeps real-world streaks, both good and bad.
- Dollars. Balances and targets must be in the same units. Comparing future, inflated balances with a target in today's dollars overstates success.
How to use it
Treat the success rate as a gauge, not a verdict. Check it once a year, look at the bad-luck outcome alongside it, and ask what would raise it most cheaply: a year more of work, a little less spending, a different Social Security claim age, or a better withdrawal and Roth conversion strategy.
Common questions
What is a good Monte Carlo success rate for retirement?
Many planners aim for roughly 80% to 95%. Below that, the plan is fragile without spending flexibility; well above it, you may be working longer or spending less than you need to.
Does a 75% success rate mean a 25% chance of running out of money?
Not quite. It means that in 25% of simulated futures, the plan as written — same spending every year, no adjustments — ran short at some point. Real retirees cut spending in bad markets, and Social Security continues regardless.
What's the difference between normal and historical Monte Carlo?
Normal mode draws each year's return at random from a bell curve with the volatility you set. Historical mode samples real past sequences of years, which keeps the fat tails and streaks of actual markets.
Why did my success rate drop when I changed nothing?
Usually an assumption changed: volatility, expected return, inflation, or how far out the plan runs. In Retirology's 2026.0.4 update, the saving-years result also dropped for most plans because it now compares balances and targets in the same dollars.