FI Calc & cFIREsim alternative
Retirology vs. free FIRE calculators
Free calculators like FI Calc and cFIREsim are a great first step: enter a portfolio and spending, and see how the plan would have fared through market history. They answer one question well. Here's what they leave out, and when it matters.
Updated October 2026
The short version
| Retirology | Free FIRE calculators | |
|---|---|---|
| Price | $19+ once; every update free | Free |
| Main question | How do I fund each year, at the lowest tax and healthcare cost? | Would this withdrawal rate have survived history? |
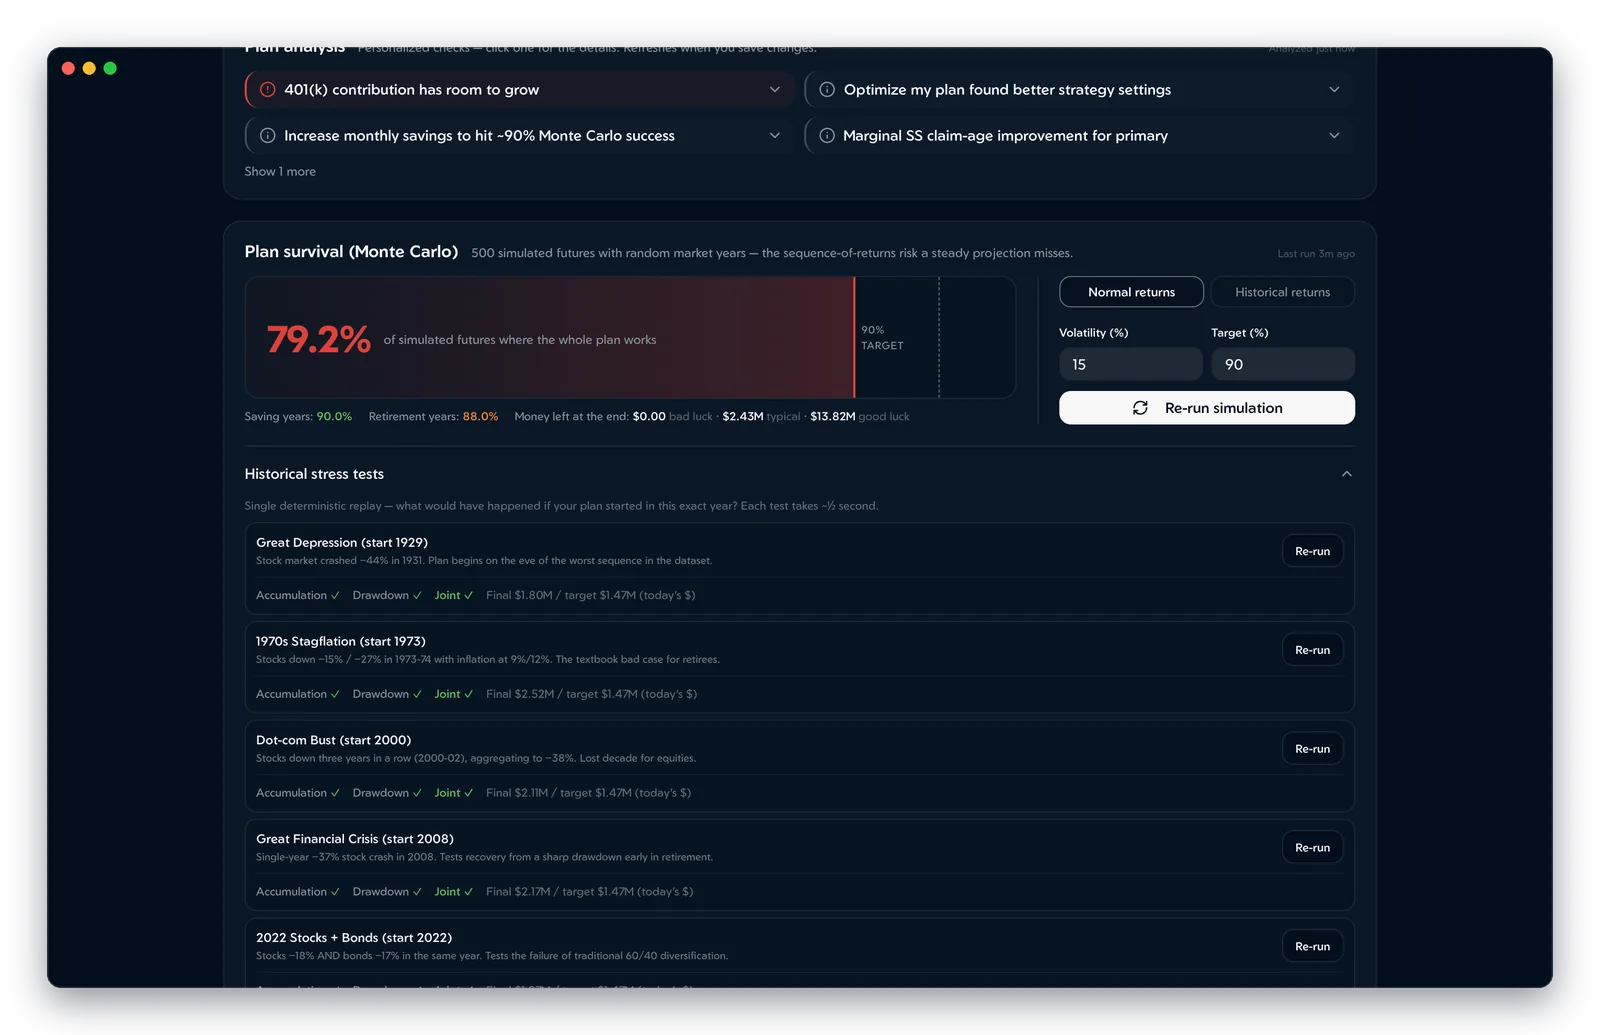
| Market history | Historical Monte Carlo + 5 named stress tests | Yes — their core feature |
| Account types | Each account tracked separately (Traditional, Roth, taxable, HSA, cash) | Usually one portfolio |
| Taxes | Federal + all 51 state codes, every year | Generally not modeled |
| Roth ladders, ACA, SEPP | Yes | No |
| Your data | On your computer | Varies by tool |
What a single-portfolio calculator misses
- Which money you spend. $80,000 from a Roth, a taxable account or a Traditional IRA are three very different tax bills.
- Getting at money before 59½. Without a Roth ladder, Rule of 55 or SEPP, Traditional money can cost a 10% penalty.
- Health insurance. In 2026 the ACA subsidy ends abruptly at 400% of the poverty line. Your withdrawal mix decides which side you land on. See the ACA subsidy cliff.
- Your state. A retired couple's state income tax ranges from $0 to over $2,000 a year depending on the state. See every state compared.
When a free calculator is enough
- You're early on and want a quick read on whether your target is in the right range.
- Most of your money is in one kind of account and taxes in retirement will be simple.
Common questions
Are FI Calc and cFIREsim good enough?
For checking whether a withdrawal rate has historically survived, yes — and they're free. They're less suited to deciding how to withdraw: which accounts to draw from, how much to convert to Roth, and how to keep ACA subsidies.
Why do taxes matter so much for early retirees?
Because the same spending can cost very different amounts depending on where it comes from. Roth conversions, ACA premiums, early-withdrawal penalties and state taxes can add up to six figures over a retirement.
Is Retirology a historical simulator too?
Yes. Alongside normal-distribution Monte Carlo it has a historical mode that samples real 1928–2024 market years, and stress tests that replay retiring in 1929, 1973, 2000, 2008 and 2022.